
LuxLoc: How To Get The Most Out Of Your Exotic Car With A Car Collateral Loan
An exotic car sitting in your garage is a strange kind of wealth. It’s worth a genuine fortune, yet unless you sell it, that value stays completely locked away, doing nothing for you financially while you cover insurance, storage, and maintenance costs just to keep it.
Vasco Assets built LuxLoc to solve exactly that problem, a secured line of credit that lets you borrow against your Ferrari, Rolls-Royce, Bentley, Maserati, or McLaren without ever giving up the keys.
Why Exotic Car Owners Are Turning to Collateral Loans
Traditional lenders rarely know how to value a rare or limited-production vehicle correctly, and even when they do, they still base approval on your credit score and income rather than the car itself. That mismatch leaves a lot of value on the table for owners who could otherwise access it easily.
Vasco Assets’ certified team specializes in exactly this kind of valuation, treating your exotic car as the real asset it is.
What Is a Car Collateral Loan?
A car collateral loan, delivered through LuxLoc, lets you pledge your exotic vehicle as security in exchange for access to a line of credit rather than selling it outright. You retain ownership and use of the car while unlocking liquidity against its value.
A Line of Credit, Not a Lump Sum
Unlike a traditional loan where you receive a lump sum and start paying interest immediately, LuxLoc functions as a revolving line. You draw only what you need, when you need it, and pay interest solely on the amount you’ve actually borrowed.
How LuxLoc Works for Exotic Vehicles
The process starts with a professional valuation of your vehicle, considering make, model, rarity, condition, mileage, and current market demand. Based on that assessment, Vasco Assets sets a credit line using a loan-to-value ratio of up to 80%.
Setup Costs and Ongoing Use
Opening the line costs roughly 0.5% of the amount you might eventually want to borrow, a fraction of what a conventional loan typically charges in fees and interest. Once established, the line sits ready for you to draw against whenever a need or opportunity arises, without any pressure to use it right away.
How Much Can You Borrow Against an Exotic Car?
Your exotic car’s market value is the starting point for determining how much liquidity it can provide, but it isn’t the same thing as your available credit. The calculation generally follows a straightforward sequence: vehicle valuation → applicable LTV → maximum credit line → amount actually drawn → interest on the outstanding balance.
Putting the Math Into Perspective
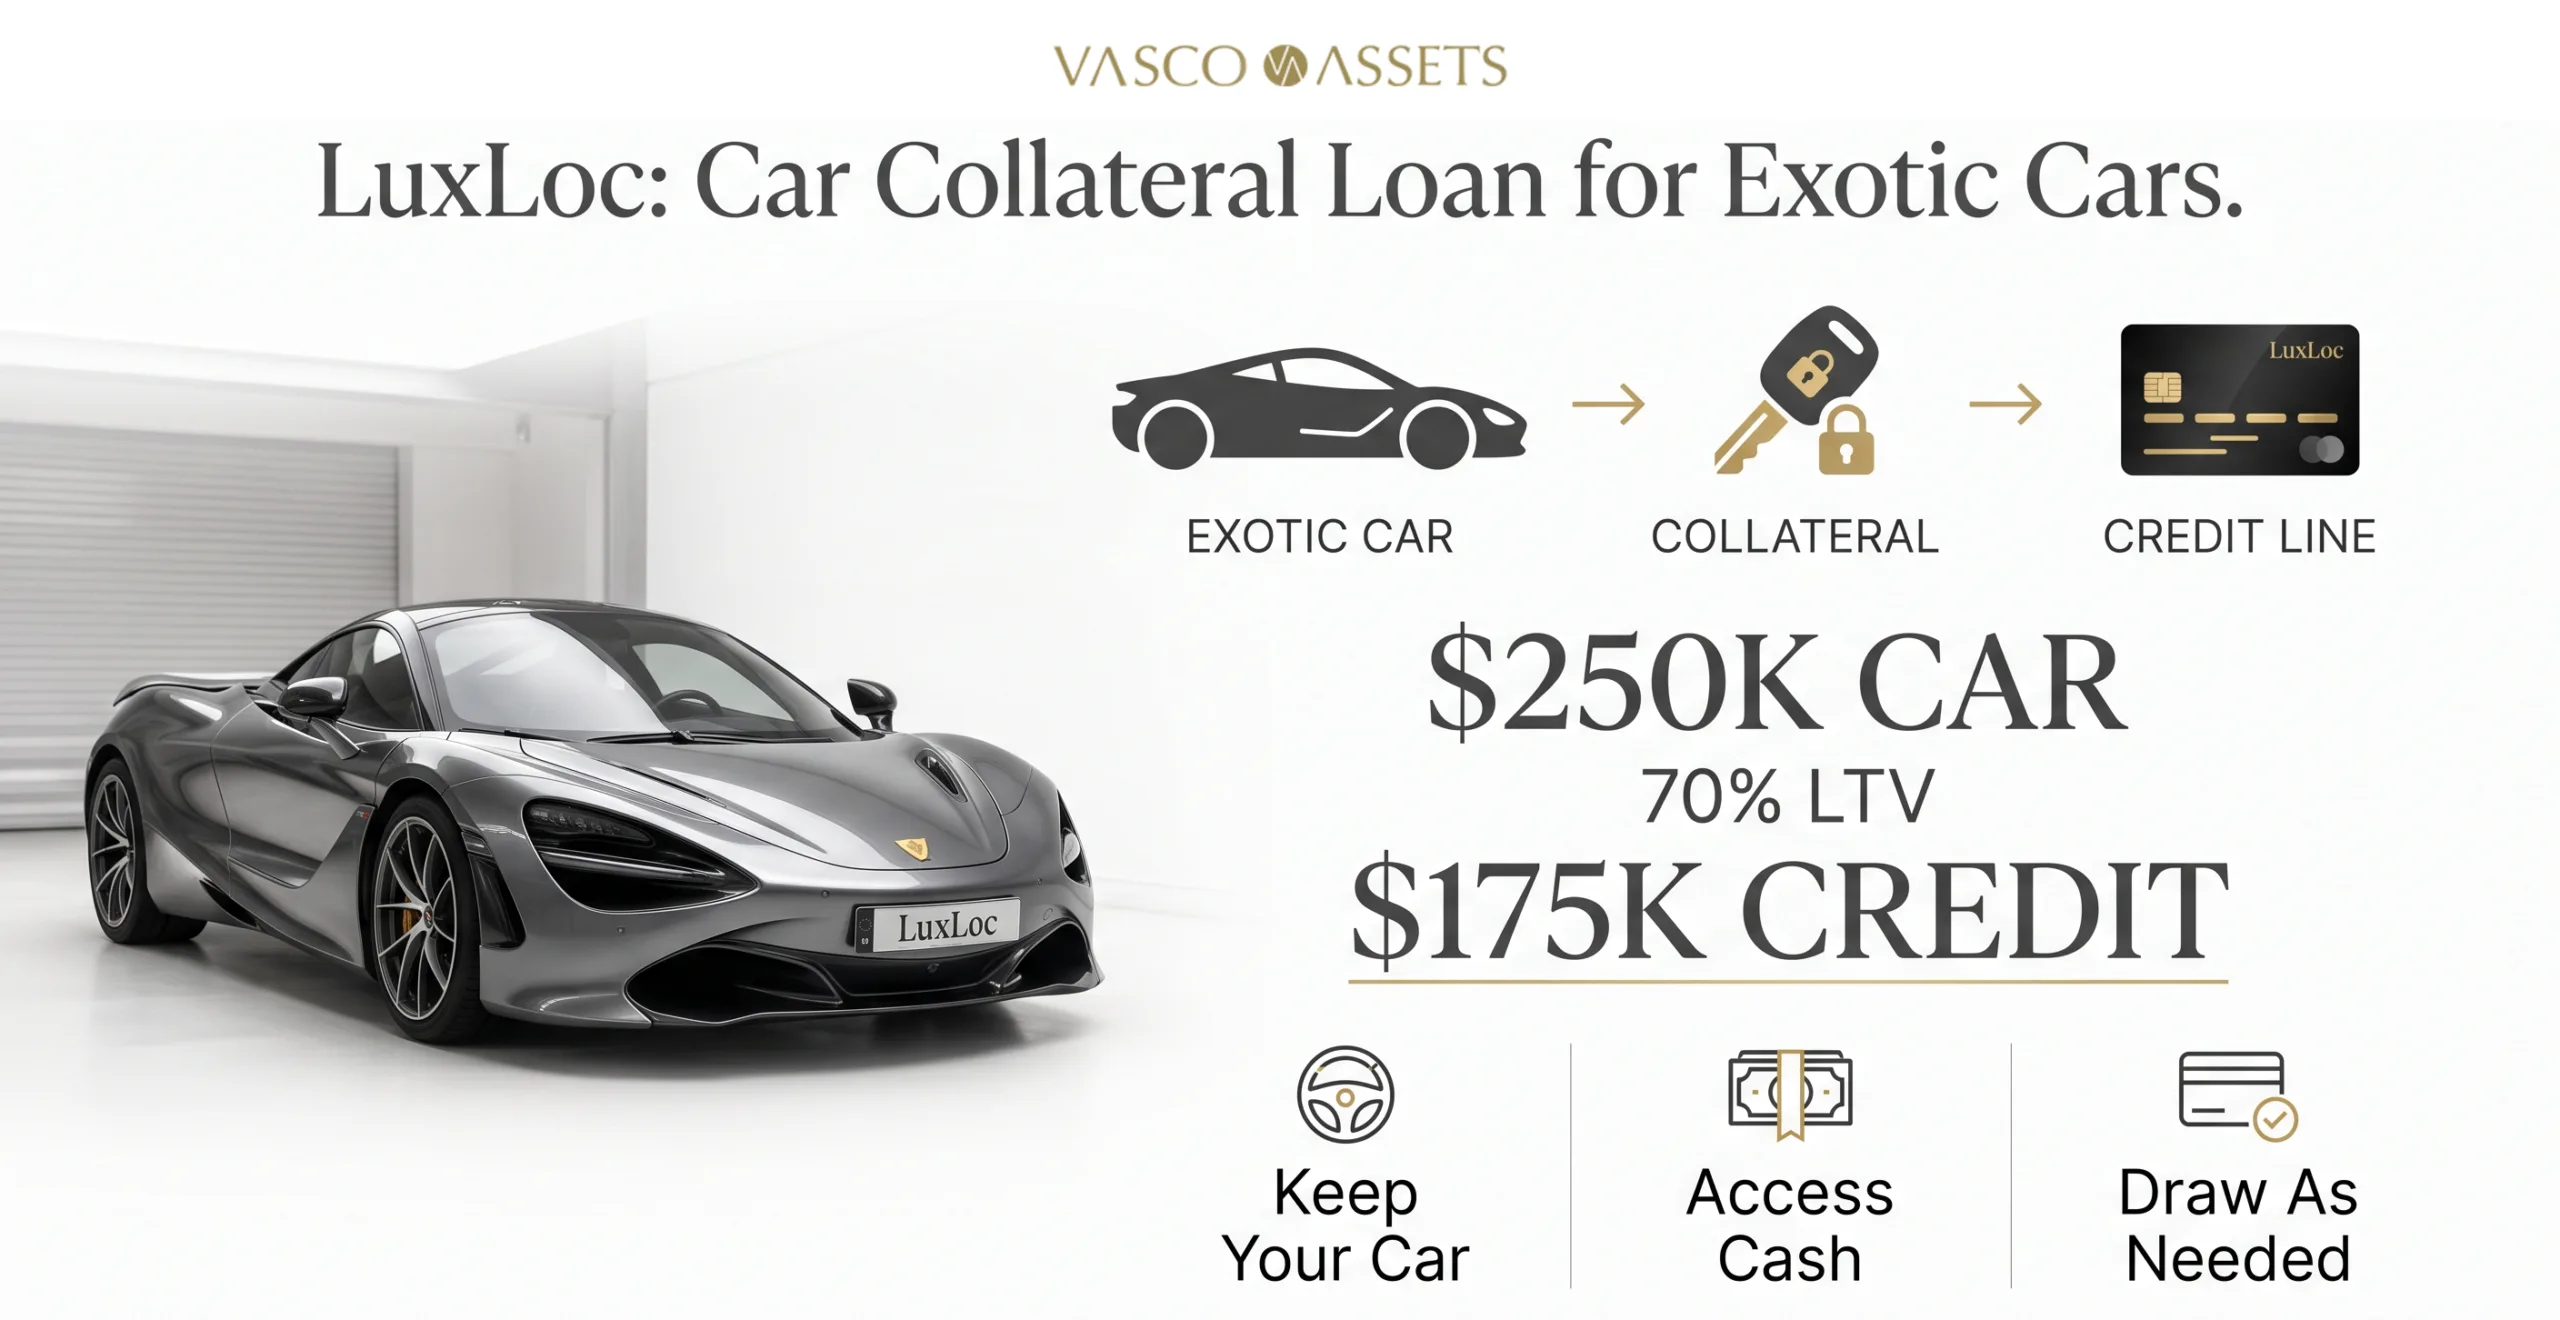
For example, if your Ferrari is valued at $250,000 and a hypothetical 70% loan-to-value applies, the maximum credit line would be $175,000, not $250,000. If you only draw $50,000 from that line, your outstanding balance is $50,000, not the entire approved limit.
What “Up to 80% LTV” Actually Means
It’s important to understand that “up to 80% LTV” doesn’t guarantee every exotic vehicle qualifies for an 80% advance. The applicable percentage can vary based on the vehicle’s condition, mileage, rarity, service history, documentation, marketability, and current secondary-market demand.
Why Condition and Rarity Change the Number
A highly desirable, well-documented vehicle with strong resale liquidity may be treated very differently from a heavily modified, high-mileage, or harder-to-resell example. This is consistent with how lenders generally treat loan-to-value across secured financing: as the CFPB explains, lenders use the ratio to determine both how much a borrower can access and the terms offered, since risk shifts with the collateral’s assessed strength.
Two Different Numbers to Keep in Mind
Collateral value and borrowing capacity are two different numbers, and it’s worth not confusing them. The vehicle must first be professionally evaluated, then the appropriate LTV is applied to that valuation to determine the potential credit limit, and your actual borrowing can be lower still since a revolving line only requires you to draw what you need.
The Bottom Line for Exotic Car Owners
A $250,000 exotic car doesn’t automatically mean $250,000 of accessible cash. The real question is how much credit your specific vehicle can support under Vasco’s valuation and LTV criteria, which is exactly why a free valuation is the only reliable way to know your real number.
Which Exotic Cars Qualify for LuxLoc
LuxLoc is designed around a specific tier of vehicles: brands like Ferrari, Rolls-Royce, Bentley, Maserati, and McLaren. To qualify, the vehicle generally needs to be valued at $10,000 or more, a threshold nearly every exotic car will clear easily.
If You Own Multiple Qualifying Vehicles
Owners with more than one qualifying vehicle, or a mix of vehicles and other luxury assets like jewelry or precious metals, can potentially use several items together to strengthen a credit line. A free valuation is the fastest way to find out what your specific collection could support.
Why a Collateral Loan Beats Selling Your Car
Selling an exotic car means giving it up permanently, along with any future appreciation it might see and the simple enjoyment of owning it. If you have a temporary cash need, a permanent sale is often the wrong tool for a short-term problem.
Keep the Car, Access the Value
A collateral loan lets you access a meaningful percentage of your car’s value while continuing to drive and enjoy it, assuming your loan terms allow for continued use. That flexibility makes LuxLoc especially appealing to collectors and enthusiasts who see their vehicles as long-term holdings, not liquid assets to cash out.
Why LuxLoc Beats a Traditional Auto-Backed Loan
Conventional lenders that offer loans against vehicles typically still weigh your credit score and income heavily, and many simply don’t have the expertise to value a rare or limited-production exotic car correctly. That mismatch often results in lower offers or outright denials for owners of genuinely valuable vehicles.
Skip the Credit Check Entirely
Because LuxLoc is secured directly by the vehicle’s assessed value, the process doesn’t require a credit check or income verification, and there’s no impact on your credit score. The vehicle itself carries the risk, which is exactly why the underwriting process can move so much faster than a bank’s.
What You Can Do With the Funds
Exotic car owners use LuxLoc credit lines for everything from funding a business opportunity to covering a major purchase in phases, drawing only what’s needed at each stage. Others use it to consolidate higher-interest debt into a single line backed by an asset they already own outright.
A Financial Safety Net, Not Just a Loan
Because the line stays open whether or not you draw from it, many owners simply set one up in advance as a safety net for whatever comes next. That’s a fundamentally different posture than scrambling for financing once a need has already become urgent.
Why Choose Vasco Assets for Your Exotic Car Loan
Vasco Assets brings certified expertise specifically in luxury and exotic vehicles to every valuation, ensuring your credit limit reflects your car’s true market value rather than a conservative, generic estimate. That expertise is backed by a reputation built on over 100 five-star reviews from clients across a range of luxury asset categories.
A Fast, Transparent Process
The evaluation and approval process is built for speed, recognizing that financial opportunities and needs rarely wait around. As a licensed and bonded, multinational firm, Vasco Assets brings the same rigor to a $10,000 valuation as it does to a seven-figure exotic car appraisal.
Put Your Exotic Car’s Value to Work Without Letting It Go
Your Ferrari, Bentley, or McLaren doesn’t have to sit in the garage as dead equity, admired but financially idle. LuxLoc lets that value quietly stand ready in the background, accessible the moment you need it, while you keep the car exactly where it belongs: in your driveway.
Curious what your exotic vehicle could unlock? Request a free, no-obligation LuxLoc valuation from Vasco Assets today and find out what kind of credit line your car could support.
Frequently Asked Questions
What is a car collateral loan through LuxLoc?
It’s a secured line of credit that uses your exotic vehicle as collateral instead of your income or credit score. You draw funds as needed and pay interest only on the amount you’ve actually used.
Which car brands qualify for LuxLoc?
Qualifying vehicles generally include brands like Ferrari, Rolls-Royce, Bentley, Maserati, and McLaren, valued at $10,000 or more. A free valuation will confirm whether your specific vehicle qualifies.
Can I still drive my car while it’s used as collateral?
Continued use depends on the specific terms of your agreement, so this is worth confirming directly during your valuation and application. Many owners specifically choose LuxLoc because it’s designed to preserve ownership rather than requiring surrender of the asset.
How much can I actually borrow against my exotic car?
Your credit line is based on a loan-to-value calculation applied to your vehicle’s assessed worth, not the full appraised value itself. A $250,000 vehicle at a 70% LTV, for example, would support a $175,000 credit line, and the exact percentage depends on condition, rarity, mileage, and marketability.
Does every vehicle qualify for the full 80% LTV?
No. “Up to 80% LTV” means that’s the ceiling, not a guarantee, and the applicable ratio varies based on the vehicle’s specific condition, documentation, and resale demand.
Will applying affect my credit score?
No. Because the line is secured by your vehicle rather than your creditworthiness, the process doesn’t require a credit check, so there’s no impact on your credit score.
How is this different from just selling my exotic car?
Selling transfers ownership permanently for a lump sum, while LuxLoc lets you retain the car and access funds only as needed. This makes it a better fit for owners who see their vehicle as a long-term holding rather than an asset they’re ready to part with.