
LuxLoc: How Vasco’s Secured Collateral Line of Credit Bolsters Your Financial Flexibility
If your wealth is tied up in things you own rather than cash sitting in a bank account, getting liquidity usually means one of two unpleasant choices: sell what you love, or beg a bank for a loan based on your credit score and income statements. There’s a third option most people never consider.
Vasco Assets built LuxLoc specifically to solve this problem, a secured line of credit that turns diamonds, gold, jewelry, and luxury vehicles into real financial flexibility without ever requiring you to give them up.
A Different Way to Think About Your Assets
Many people own items they don’t consider “assets” at all, fine jewelry, inherited watches, precious stones, or a luxury car sitting in the garage. LuxLoc treats these holdings as exactly what they are: real, bankable value.
That shift in perspective is the whole idea behind Vasco Assets’ approach to lending, and it’s why so many owners of luxury goods are rethinking what their possessions can actually do for them.
What Is a Secured Line of Credit?
A secured line of credit is a revolving pool of money you can draw from whenever you need it, backed by collateral instead of your credit score or employment history. Unlike a traditional loan, you’re not handed a lump sum you immediately start repaying interest on from day one.
Access Funds Only When You Need Them
Instead, you unlock access to funds and pay only for the portion you actually use, whenever you choose to use it. This makes a secured line fundamentally different from a home equity loan or personal loan, where interest accrues on the full amount immediately regardless of whether you’ve spent it.
Why Collateral Changes the Equation
Because the lender’s risk is tied to a tangible asset rather than your financial history, the entire approval process looks different from a conventional credit product. This is precisely what allows LuxLoc to move faster and require far less paperwork than a bank would typically ask for.
How LuxLoc Actually Works
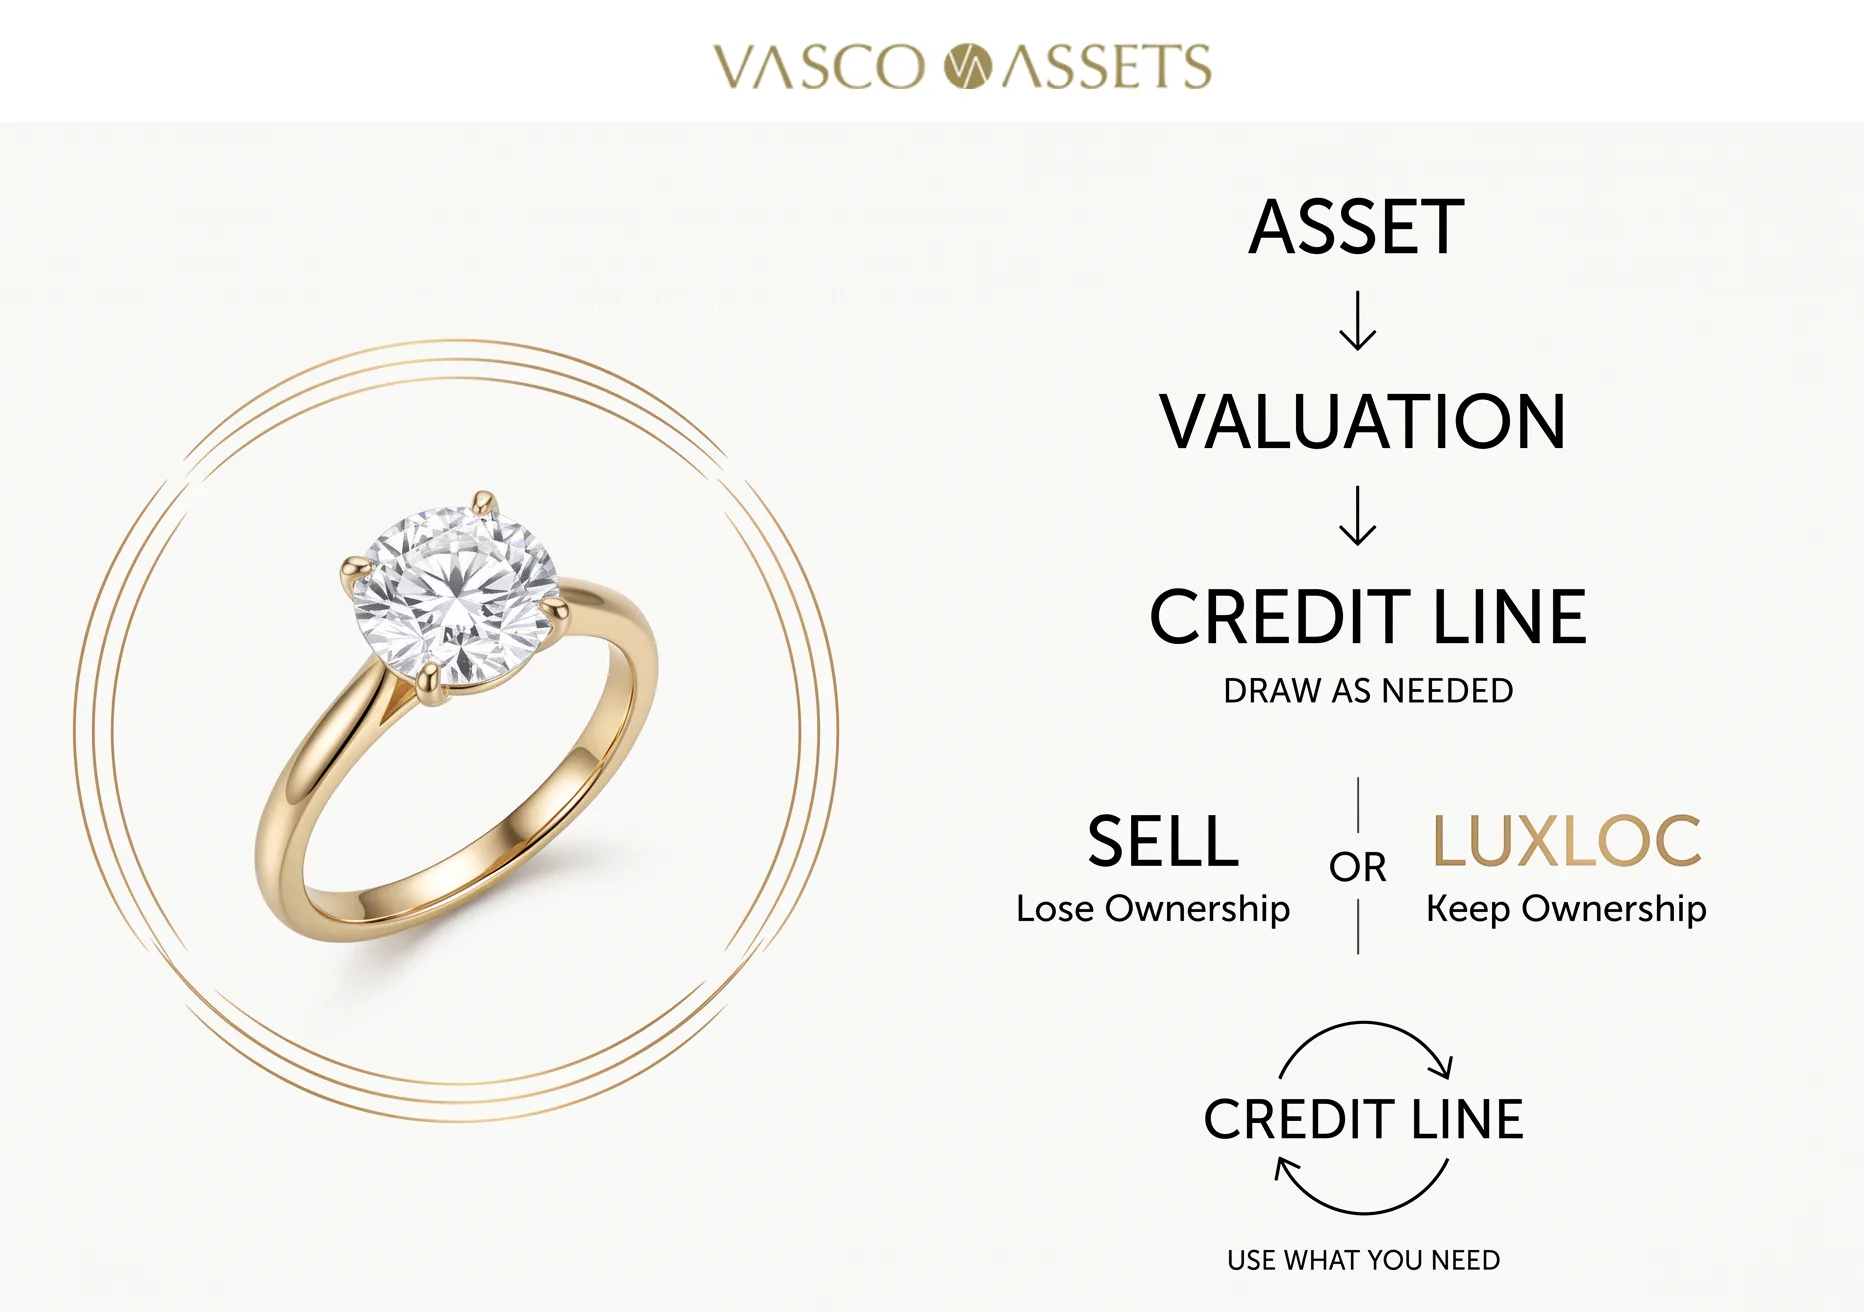
The mechanics start with pledging an asset rather than selling it. Vasco Assets evaluates the item, and instead of a lump-sum loan, you’re granted a credit line set at a loan-to-value ratio of up to 80%, depending on the asset class.
What It Costs to Open a Line
Securing that credit line costs roughly 0.5% of the amount you might eventually want to borrow, a fraction of the cost of a full traditional loan. Once it’s set up, the line simply sits available, ready whenever an opportunity or need arises, with no pressure to use it right away.
Draw as Needed, Pay for What You Use
From there, you draw funds in whatever amounts you choose, up to your limit, and interest applies only to what you’ve actually drawn. That structure makes LuxLoc especially useful for ongoing expenses like a home renovation or a phased business investment, rather than a single upfront cost.
How Much Can You Borrow Against Your Luxury Assets?
The value of a luxury asset does not automatically equal the amount you can borrow against it. The key calculation is the loan-to-value ratio, which compares the amount financed with the value assigned to the collateral, and it’s the same metric lenders across nearly every type of secured financing use to set terms.
The Path From Valuation to Credit Line
For a LuxLoc line, the process flows like this: asset valuation → applicable LTV → maximum credit line → amount actually drawn → interest on the outstanding balance. Each step narrows the number further, from what your asset is worth to what actually lands in your account.
Putting the Math Into Perspective
For example, if an eligible diamond, jewelry collection, or luxury vehicle is valued at $100,000 and a hypothetical 70% LTV applies, the resulting maximum credit line would be $70,000, not the full $100,000. If you subsequently draw $25,000 from that line, your outstanding borrowing is $25,000, not the entire approved limit.
What “Up to 80% LTV” Really Means
It’s worth understanding that “up to 80% LTV” doesn’t guarantee every asset qualifies for that top rate. The applicable percentage can vary by asset class, valuation, condition, documentation, marketability, and the lender’s underwriting criteria.
Why Lenders Rely on LTV in the First Place
The Consumer Financial Protection Bureau explains that lenders use the loan-to-value ratio to determine both how much a borrower can access and the terms offered, since a higher LTV generally represents greater risk to the lender. That’s the same principle behind why LuxLoc’s rate varies by asset rather than applying one flat percentage to everything.
The Takeaway for Estimating Your Liquidity
A $100,000 valuation is a starting point, not a promise of $100,000 in available cash. Your final credit limit depends on Vasco’s assessment of the collateral and the terms of your specific LuxLoc agreement, which is exactly why a free valuation is the only reliable way to know your real number.
What Assets Qualify for LuxLoc
LuxLoc is built around a specific category of holdings: diamonds, fine jewelry, gold, precious metals, and select luxury vehicles from brands like Ferrari, Rolls-Royce, Bentley, Maserati, and McLaren. Qualifying items must be valued at $10,000 or more.
If Your Asset Falls Below the Threshold
Assets valued under that threshold may still qualify for a standard collateral loan instead of a LuxLoc line. Either way, a free valuation is the fastest way to find out which option fits your specific holdings.
Real-World Ways People Use a LuxLoc Line
Because LuxLoc is a revolving line rather than a one-time loan, it tends to fit situations where money is needed in phases rather than all at once. A home renovation is a classic example, where costs arrive in stages across contractors, materials, and unexpected changes along the way.
Business Opportunities and Debt Consolidation
Business owners often use a line like this to fund inventory purchases or bridge cash flow gaps without diluting equity or taking on a rigid loan structure. Others use it to consolidate higher-interest debt into a single line backed by an asset they already own, often at a considerably lower rate than an unsecured card or loan would offer.
Flexibility for Whatever Comes Next
Because the line stays open whether or not you draw from it, many owners simply set one up as a financial safety net for opportunities or emergencies they can’t yet predict. That’s a meaningfully different posture than taking on debt reactively once a need has already become urgent.
LuxLoc vs. Traditional and Unsecured Credit
An unsecured line of credit relies entirely on your creditworthiness, meaning your credit score and debt-to-income ratio determine whether you’re approved at all. A strong credit history can still result in a denial if too much of your income is already committed to other debt, or if your employment status has recently changed.
Why Secured Credit Skips the Red Tape
Because LuxLoc is backed by a tangible asset, the risk shifts away from your credit profile and onto the value of the collateral itself. This means the process can skip income verification and credit checks almost entirely, with no impact on your credit score regardless of outcome.
Why Choose Vasco Assets for LuxLoc
Vasco Assets brings certified expertise in diamonds, precious metals, and luxury vehicles to every valuation, ensuring your credit limit reflects your asset’s true worth rather than a conservative guess. That expertise, paired with a track record of over 100 five-star reviews, means you’re working with a team that understands luxury assets inside and out.
A Process Built for Speed
The company has simplified its approval process because it recognizes how much timing matters in financial decisions, completing evaluations quickly so you can access funds without unnecessary delay. Combined with secure, insured shipping for items sent in for appraisal, the entire process stays fast and protected from start to finish.
A Firm Built on Global Reach
As a licensed and bonded investment firm with a multinational presence, Vasco Assets brings the same accuracy and market awareness to a LuxLoc valuation that it applies to outright purchases. That global perspective means your asset is measured against real market data, not a single local opinion.
Let Your Assets Work Harder Than a Drawer or Garage Ever Could
Your luxury holdings don’t have to sit idle waiting for a rainy day or a decision to sell. LuxLoc lets diamonds, gold, jewelry, and luxury vehicles quietly back real financial flexibility in the background, ready the moment you need it and costing you very little when you don’t.
Curious what your holdings could unlock? Request a free, no-obligation LuxLoc valuation from Vasco Assets today and see what kind of credit line your assets could support.
Frequently Asked Questions
What exactly is LuxLoc?
LuxLoc is a secured line of credit from Vasco Assets that uses diamonds, jewelry, gold, precious metals, or luxury vehicles as collateral instead of your income or credit score. You draw funds as needed and only pay interest on the amount you actually use.
What assets qualify for a LuxLoc line of credit?
Qualifying assets include diamonds, fine jewelry, gold, precious metals, and select luxury vehicles such as Ferrari, Rolls-Royce, Bentley, Maserati, and McLaren. Items must be valued at $10,000 or more to be eligible.
How much can I actually borrow against my asset?
Your credit line is calculated using a loan-to-value ratio, not the full appraised value of your asset, so a $100,000 item won’t necessarily unlock $100,000 in credit. The exact percentage depends on the asset class, condition, documentation, and underwriting factors lenders typically weigh.
Will applying for LuxLoc affect my credit score?
No. Because LuxLoc is secured by collateral rather than your creditworthiness, it doesn’t require a credit check, so there’s no impact on your credit score during the process.
Do I have to use the full credit line once it’s approved?
No. LuxLoc is a revolving line, meaning you can draw as little or as much as you need at any given time, up to your limit, and you’re only charged interest on what you actually use.
What happens to my asset while I have a LuxLoc line open?
The asset is held as collateral for the term of the agreement, similar to any secured lending arrangement. If you don’t draw against the line, holding it open costs you very little beyond the initial setup fee.
How is LuxLoc different from simply selling my asset?
Selling transfers ownership permanently in exchange for a lump sum, while LuxLoc lets you retain ownership and access funds only as needed. This makes it a better fit if you expect to want the asset back or believe its value may increase over time.