
Diamond Collateral Loan: Borrow Against High-Value Diamonds
A high-quality diamond is one of the most concentrated forms of wealth you can own. Yet when a business opportunity, tax bill, or unexpected expense arrives, that value sits locked in a ring, a pendant, or a parcel of loose stones. Selling may mean accepting a rushed offer and losing a piece you hoped to keep for a lifetime.
A diamond collateral loan lets you unlock that value without giving up ownership. At Vasco Assets, a licensed and bonded firm in Newport Beach, our certified diamond buyers provide free valuations and no-credit-check financing, backed by over 150 years of combined luxury experience. Here’s how borrowing against your diamonds works and how to secure the strongest offer.
Brilliance as Collateral: How Diamond Loans Work
A diamond collateral loan uses your stone or jewelry, rather than your credit history, to secure the funds you borrow. The loan amount is based on a percentage of the diamond’s resale value, and you reclaim your piece once the loan and fees are repaid. Learn more in our guide to getting a loan with diamonds.
Because it’s a collateral loan, it won’t appear on your credit whether or not it’s repaid. That privacy makes collateral loans appealing to individuals and business owners alike. The trade-off: failing to repay means forfeiting the diamond.
From Appraisal to Advance: How Your Diamond’s Value Becomes a Loan
A loan rarely equals your diamond’s full value. Lenders apply a loan-to-value (LTV) ratio to account for resale uncertainty, market demand, and the cost of recovering funds if repayment fails. These hypothetical examples are not verified Vasco Assets ratios or guaranteed offers:
| Appraised collateral value | Example LTV | Potential loan |
| $5,000 | 40% | $2,000 |
| $10,000 | 50% | $5,000 |
| $20,000 | 60% | $12,000 |
Lenders focus on resale value, not retail price or insurance replacement cost. The 4Cs, origin, documentation, and demand all shape it, as GIA’s diamond buying guide explains. Policies vary: Diamond Banc’s FAQ cites an LTV of 65% to 75% of estimated liquid wholesale value, though that’s no universal standard. Get the collateral value, LTV, and total cost in writing.
Natural vs. Lab-Grown: Why Origin Matters to Lenders
A diamond’s origin can dramatically change its collateral value. Natural diamonds benefit from finite supply and a deep global trading network, which gives lenders confidence that a stone can be resold. During recent price declines, larger and higher-quality natural stones held up better than smaller, lower-grade ones.
Lab-grown diamonds are a different story. One jeweler reports that lab-grown stones typically resell for 10–30% of their price, often less, with no established secondary market. Because a lender’s offer depends on resale value, lab-grown pieces usually support far smaller loans, if any.
Paper Trail: Preparing Your Diamond for Appraisal
Documentation speeds approval and strengthens your offer. Bring any grading reports, appraisals, and purchase receipts. If your diamond has a GIA report, you can confirm its details through GIA Report Check, the institute’s secure online database.
For added security, check whether the report number is laser-inscribed on the diamond’s girdle. Clean your jewelry gently before your appointment, and note any settings or accent stones. Even without paperwork, our specialists can evaluate your diamond in person.
Loose Stones, Rings, and Collections: Choosing Your Structure
A traditional collateral loan delivers a fixed sum upfront, ideal for a single, known expense. Vasco offers a minimum loan of $2,500, with negotiable rates between 2% and 10% that average 5%. Owners of a single ring can explore our guide to a loan against a diamond ring.
For larger holdings, LuxLoc offers a flexible credit line. With an LTV of up to 80%, loose diamonds appraised at $50,000 could unlock a credit line near $40,000 while you keep the stones. Securing the line costs roughly 0.5% of the amount you might borrow, and interest begins only when you draw funds.
Why Diamond Owners Choose Vasco Assets
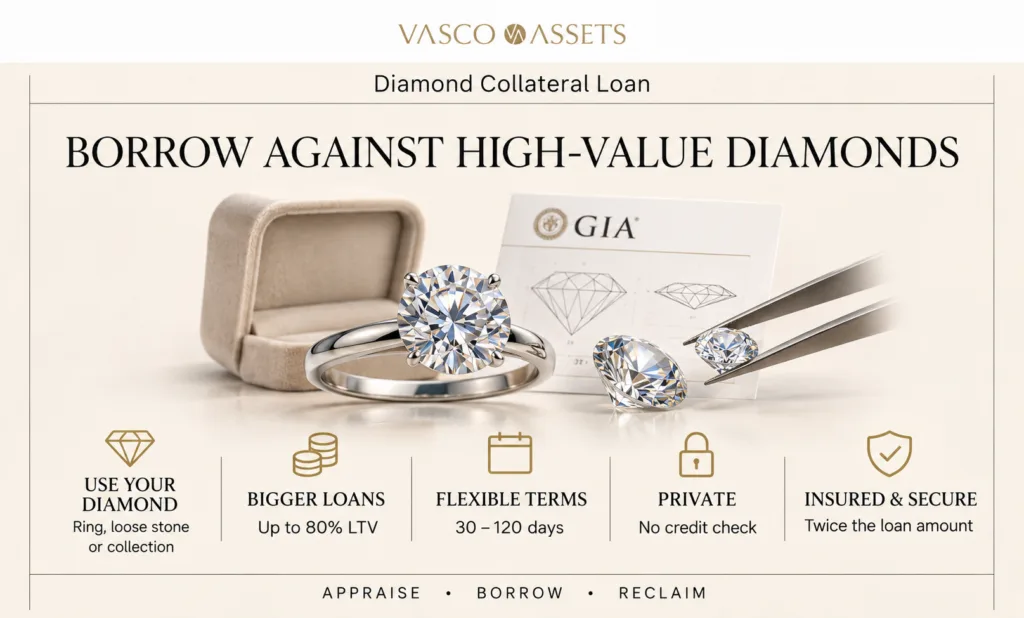
Vasco Assets pairs certified diamond expertise with flexible lending. Collateral loans run 30 to 120 days with no credit check required, and funds can be available in as little as 24 hours. Pledged assets are insured by Lloyd’s and Partners of London for twice the loan amount and stored in secure vaults.
Sure Secure Shipping lets owners outside Orange County send diamonds safely. If you’d rather part with a stone, our team can help you sell your diamond or reach buyers through consignment services.
Keep the Sparkle, Unlock the Capital
A diamond collateral loan turns your most brilliant asset into fast, private funding without a credit check or a permanent sale. Choose a lender with certified diamond expertise, bring your documentation, and understand your total cost upfront. Done right, you’ll have the capital you need and your diamond back where it belongs.
Ready to see what your diamonds can unlock? Request your free valuation from Vasco Assets, or call 949.674.3575 to speak with our certified diamond specialists today. We’ll give you a clear, honest offer and guide you through every step.
Frequently Asked Questions
Can I get a diamond loan without a credit check?
Yes. Vasco Assets offers collateral loans against jewelry and other luxury assets with no credit check required. Approval depends on your diamond’s quality, authenticity, and market value rather than your income or credit history.
The loan also won’t appear on your credit report, regardless of whether it’s repaid.
Can I borrow against a lab-grown diamond?
It’s possible in some cases, but loan amounts are typically much lower than for comparable natural stones. Lab-grown diamonds face falling prices and a thin resale market, which limits what any lender can safely advance.
If you’re unsure of your diamond’s origin, our specialists can confirm it during your free valuation.
Can I borrow against my engagement ring?
Yes. Engagement rings are among the most common diamond pieces used as collateral, and you can reclaim yours once the loan is repaid. The center stone typically drives most of the value, while the setting and accent diamonds add to it.
Pledging the ring lets you access capital while keeping it, rather than choosing between sentiment and cash flow.
Do I need a GIA grading report?
A report isn’t always required, but it helps considerably. Independent grading gives lenders confidence in your diamond’s 4Cs, which often leads to stronger offers and faster approvals.
If you don’t have a report, our certified diamond buyers can assess the stone in person and advise whether certification is worth pursuing.
How long does a diamond collateral loan last?
Standard terms run 30, 60, 90, or 120 days, and you can redeem at any time before the term ends. Repaying early can reduce your total borrowing cost.
At the end of the term, you may request an extension by paying the fees from the original agreement, after which a new loan agreement is issued.
Is my diamond insured while it’s held as collateral?
Yes. Assets held by Vasco are insured by Lloyd’s and Partners of London for twice the loan amount and stored in secure vaults. You remain the legal owner throughout the loan, and your diamond is returned once you repay.
What happens if I can’t repay my diamond loan?
If a loan isn’t repaid, it defaults and the collateral becomes the property of Vasco Assets. There’s no damage to your credit, but you lose the pledged diamond.
If repayment looks difficult, contact our team before the term ends. An extension may give you the time you need to repay and reclaim your piece.