
Loan Against Gold Jewelry: Access Cash Without Selling
Your gold jewelry holds more than sentimental value. With gold prices near historic highs, those chains, bracelets, and rings may represent thousands of dollars in untapped capital. But selling a family heirloom, or a piece you simply love, to cover a short-term expense can feel like a permanent answer to a temporary problem.
A loan against gold jewelry lets you unlock that value and get your pieces back once you repay. At Vasco Assets, a licensed and bonded firm in Newport Beach, we offer free valuations and no-credit-check financing, backed by over 150 years of combined luxury experience. Here’s how gold jewelry loans work and how to get the most from yours.
Gold in the Vault, Cash in Hand: How Gold Jewelry Loans Work
A gold jewelry loan is a collateral loan secured by your pieces instead of your credit history. You hand your jewelry to the lender for safekeeping, receive your funds, and reclaim everything once the loan and fees are repaid. Through our loans against gold jewelry, California clients can unlock the value of their gold without selling it.
Because it’s a collateral loan, it won’t appear on your credit whether or not it’s repaid. That privacy makes collateral loans attractive to individuals and business owners alike. The trade-off: if the loan defaults, the collateral becomes the lender’s property.
From Grams to Dollars: How Gold Jewelry Becomes a Loan Amount
Your loan depends on more than weight. Lenders weigh purity, the current gold price, and the loan-to-value (LTV) ratio they offer. As the Federal Trade Commission explains, a higher karat rating means a higher proportion of gold. So a 20-gram 18K necklace, at 75% gold, holds about 15 grams of fine gold:
| Calculation | Example |
| Necklace gross weight | 20 grams |
| Gold purity | 18K (75%) |
| Fine-gold equivalent | 15 grams |
| Hypothetical gold price | $100 per gram |
| Estimated metal value | $1,500 |
| Hypothetical LTV | 60% |
| Potential loan before fees | $900 |
These figures are illustrative, not a current price or a Vasco Assets quote. Lenders also adjust for non-gold parts; IDFC FIRST Bank’s gold-collateral valuation methodology, for instance, deducts any non-gold items from gross weight to arrive at net weight, though its criteria are its own. Appraisals may also reflect gemstones, designer value, and resale demand, so always request an itemized valuation.
More Than Melt Value: Designer, Estate, and Signed Pieces
Not all gold jewelry is valued by weight alone. Signed pieces from major luxury houses, antique estate jewelry, and items set with diamonds or fine gemstones may carry value well beyond their gold content. A generalist buyer might price them as scrap, while a specialist recognizes their collector premium.
Vasco’s team has certified expertise across signed jewelry from leading houses including Van Cleef & Arpels, Cartier, Bulgari, Harry Winston, and Tiffany & Co. Learn more in our guide to selling or borrowing against designer jewelry.
Lump Sum or Revolving Line: Collateral Loans vs. LuxLoc
A traditional collateral loan delivers a fixed amount upfront and works well for a single, known expense. Vasco offers a minimum loan of $2,500, with negotiable rates between 2% and 10% that average 5%. It’s also the right fit for smaller collections.
For larger holdings, LuxLoc offers flexibility. Gold, jewelry, and precious metals valued at $10,000 or more qualify, with credit lines set at a loan-to-value ratio of up to 80% depending on the asset class. Securing the line costs roughly 0.5% of the amount you may borrow, and interest only begins once you draw funds.
Terms, Rates, and Safekeeping: What to Expect
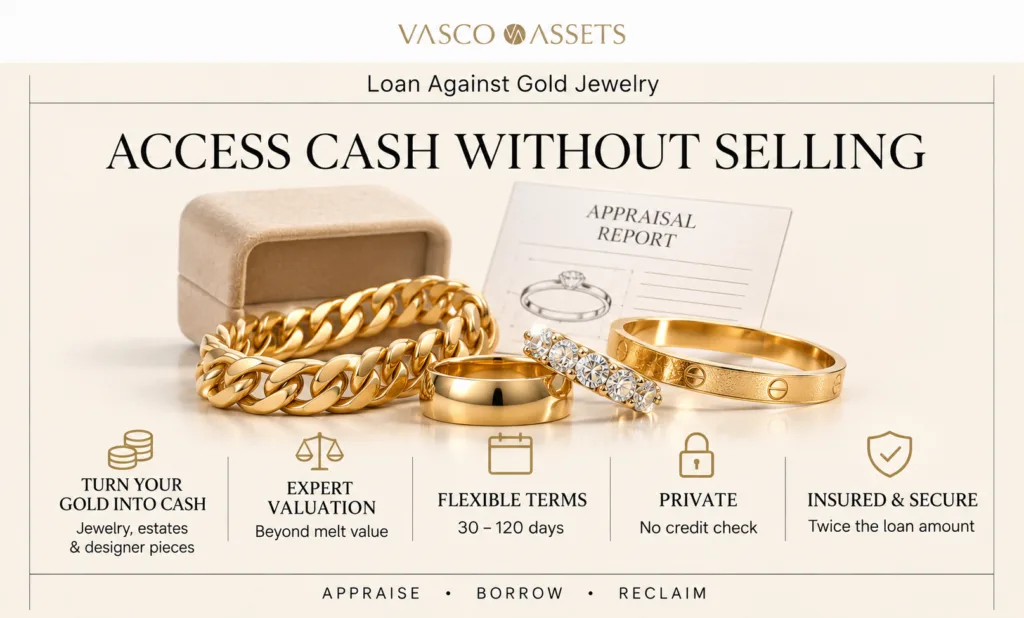
Collateral loans are typically offered on 30, 60, 90, or 120-day terms, and you can redeem at any time before the term ends. No credit check is required, and funds can be available in as little as 24 hours. Fees cover costs like bookkeeping, transport, storage, and insurance.
Your jewelry is protected throughout. Assets are insured by Lloyd’s and Partners of London for twice the loan amount and stored in secure vaults. Before signing with any lender, ask for your total repayment in dollars, including every fee, so you can compare offers accurately.
Why Gold Owners Choose Vasco Assets
Clients rely on Vasco Assets for precise evaluation, secure handling, and professional service. Valuations are free, and Sure Secure Shipping lets owners outside Orange County send jewelry safely. Businesses benefit too: we once provided an Orange County jeweler a $75,000 asset-backed loan on scrap gold and unsold jewelry.
If you’d rather part with certain pieces, we can help you sell your assets or reach buyers through consignment services. Jewelers can also explore our guide on leveraging scrap gold and unsold inventory.
Let Your Gold Work for You
A gold jewelry loan turns pieces sitting in your jewelry box into fast, private funding, without a credit check or a permanent sale. Choose a specialist lender, understand how karat and weight shape your offer, and know your total cost upfront. Done right, you’ll get the cash you need and your jewelry back.
Ready to see what your gold can unlock? Request your free valuation from Vasco Assets, or call 949.674.3575 to speak with our lending specialists today. We’ll give you a clear, honest offer and guide you through every step.
Frequently Asked Questions
Does a gold jewelry loan affect my credit score?
No. A Vasco Assets collateral loan won’t appear on your credit, whether or not it’s repaid. Approval depends on your jewelry’s value rather than your income or credit history, so there’s no hard inquiry during the process.
What is today’s gold price, and how does it affect my loan?
Gold prices change daily, and your offer reflects the market on the day of your appraisal. On October 19, 2026, gold closed at roughly $4,146 per ounce, or about $133 per gram.
Higher prices generally mean higher loan amounts for the same piece. Vasco’s minimum loan is $2,500.
Does gold-plated jewelry qualify for a loan?
Usually not in a meaningful way. Gold-plated jewelry has only a layer of at least 10K gold bonded to a base metal, so it carries little collateral value compared with solid karat gold.
Check your pieces for karat stamps such as 10K, 14K, or 18K. Our specialists can test any unmarked items during your free valuation.
What happens if gold prices change during my loan?
Your loan amount is set at the start based on that day’s appraisal. If you extend, principal and rates usually stay the same unless the asset’s value has fluctuated.
With LuxLoc, rising prices can work in your favor. If an item’s market value increases, the principal limit can be raised and more funds made available.
Is my jewelry safe while it’s held as collateral?
Yes. Pledged assets are insured by Lloyd’s and Partners of London for twice the loan amount and kept in secure vaults. You remain the legal owner throughout the loan, and your pieces are returned once you repay.
Can a business borrow against gold inventory?
Yes. Jewelers and retailers can use scrap gold and slow-moving inventory as collateral for working capital. One jeweler chose a loan over selling because they expected gold prices to keep rising over the long term.
What happens if I can’t repay my loan?
If a loan isn’t repaid, it defaults and the collateral becomes the property of Vasco Assets. There’s no damage to your credit, but you lose the pledged jewelry.
At the end of the term, you can request an extension by paying the fees from the original agreement, after which a new loan agreement is issued. Contact our team early if repayment looks difficult.