
Need to Know About Luxury Asset Lending
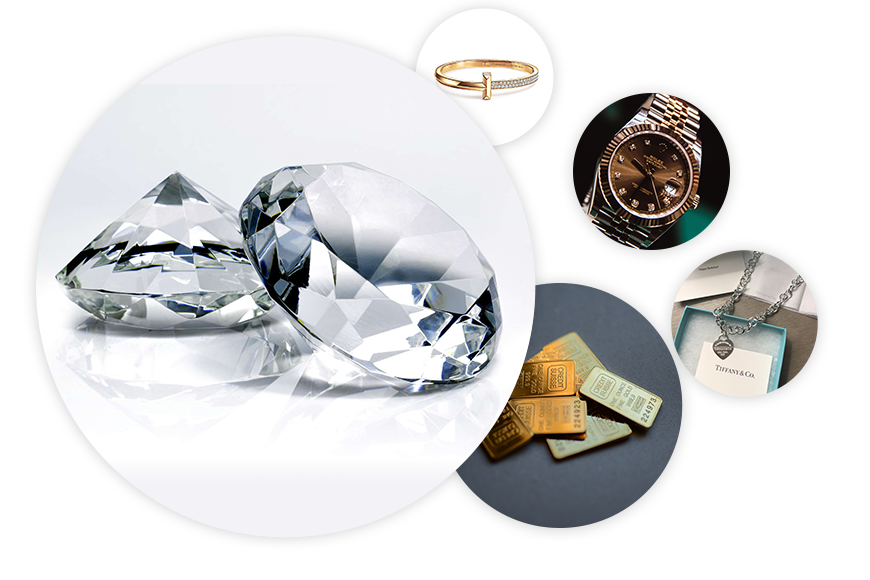
Luxury asset lending lets you unlock cash from things you already own — diamonds, gold, watches, jewelry, luxury vehicles — without selling them or going through a bank’s credit-based approval process. It’s a financing category most people don’t think about until they need it, and by then, understanding how it actually works matters a lot.
Vasco Assets, a licensed and bonded luxury asset firm based in Newport Beach, offers both collateral loans and a revolving LuxLoc line of credit, giving borrowers options built around the value of what they own.
What Luxury Asset Lending Actually Is
Luxury asset lending uses a physical, valuable possession as collateral instead of your credit score or income. You pledge the asset, a lender appraises it, and you receive financing based on that appraised value rather than a review of your financial history. The lender holds the asset securely for the loan term; you retain ownership and reclaim it once the balance is repaid.
This differs fundamentally from conventional bank financing, which centers on income verification, debt ratios, and credit checks. Luxury asset lending shifts that underwriting entirely onto the item itself, which is why it can move faster and skip much of the paperwork a bank requires.
Luxury Asset Loan vs. Bank Loan: What’s Different?
For many borrowers, the biggest question isn’t whether they can access financing — it’s which type of financing makes the most sense for their situation. Traditional bank loans and luxury asset lending both provide access to capital, but they evaluate eligibility in fundamentally different ways.
A traditional bank loan typically focuses on the borrower’s financial profile, including factors such as credit history, income, and existing debt obligations. The Consumer Financial Protection Bureau (CFPB) outlines how creditors evaluate applications based on factors like income, credit history, and other elements of a borrower’s financial circumstances.
Luxury asset lending takes a different approach by focusing primarily on the value of the pledged asset — such as diamonds, fine jewelry, luxury watches, gold, or collectible vehicles. Instead of relying primarily on credit history, the lender evaluates the asset’s authenticity, condition, market demand, and resale potential to determine borrowing capacity.
| Factor | Luxury Asset Lending | Traditional Bank Loan |
| Approval basis | Asset value and appraisal | Credit profile, income, and financial history |
| Collateral | Luxury assets such as watches, diamonds, jewelry, or vehicles | May be secured by property or may be unsecured |
| Credit inquiry | Typically not required with asset-based structures | Usually part of the approval process |
| Funding speed | Often faster after asset evaluation | Often involves longer underwriting |
| Ownership | Asset ownership is retained after repayment | Depends on the loan structure |
The key advantage of luxury asset lending is that valuable possessions can become a source of liquidity without requiring a permanent sale. A collector who owns a valuable watch, for example, may prefer borrowing against it rather than selling it and losing future ownership. Ultimately, the right choice depends on what matters most: qualifying based on financial history, or unlocking capital from assets you already own.
What Assets Qualify
Not every valuable item qualifies for this type of lending, but the category is broader than most people expect. Vasco Assets accepts diamonds, jewelry, gold, precious metals, and select luxury vehicles like Ferrari, Rolls-Royce, Bentley, and McLaren, with a minimum appraised value of $10,000 to qualify.
The asset needs to have a recognizable, liquid market — something a lender could confidently resell if it ever came to that. This is why diamonds, gold, and high-end vehicles work well as collateral, while more idiosyncratic or hard-to-appraise items generally don’t.
Lump Sum vs. Revolving Credit: Two Structures to Choose From
Luxury asset lending isn’t a single product — it typically comes in two structures. A collateral loan disburses a fixed lump sum upfront, which you begin repaying immediately, making it well suited to a known, one-time expense. A LuxLoc line of credit works differently: you secure access to funds for a small fraction of the potential loan value — roughly 0.5% — and only start paying interest once you actually draw on it.
| If you need… | Better structure |
| A fixed, one-time amount | Collateral loan |
| Ongoing or uncertain access to capital | LuxLoc line of credit |
| Immediate funds for a known expense | Collateral loan |
| Capital on standby for future opportunities | LuxLoc line of credit |
Neither structure is inherently better — it depends on whether your need is fixed or flexible.
How Much You Can Borrow
Borrowing capacity is generally expressed as a loan-to-value (LTV) ratio — the percentage of an asset’s appraised value a lender is willing to finance. LuxLoc and standard collateral loans through Vasco Assets offer LTV up to 80%, depending on the asset class and its liquidity.
| Asset Value | Approximate 80% LTV Credit or Loan Amount |
| $25,000 | $20,000 |
| $50,000 | $40,000 |
| $100,000 | $80,000 |
| $500,000 | $400,000 |
These figures are illustrative. The exact amount always depends on a professional appraisal, the asset’s condition, and current market demand for that specific item.
Terms, Fees, and What to Expect
Understanding the numbers upfront prevents surprises later. Standard credit lines and loans through Vasco Assets range from $20,000 to $99,999 in principal, with custom terms available above $100,000 based on the asset and loan-to-value ratio. Terms typically run six or twelve months, and clients in good standing can renew and extend indefinitely.
There’s no origination fee, no appraisal fee, and no credit inquiry with either structure, so applying never touches your credit bureau file. A recurring maintenance fee covers insurance, storage, and administration, charged every 30 days regardless of use, with a 10-day grace period on any missed payment before a late fee applies.
How Your Asset Is Protected While Pledged
Handing over something valuable naturally raises questions about how it’s cared for. Under Article 9 of the Uniform Commercial Code (UCC), a secured party holding collateral has a legal duty to exercise reasonable care in its custody and preservation, and the asset must remain identifiable while in the lender’s possession.
Reputable lenders typically document an asset’s condition through photographs, serial numbers, and grading or authentication reports before accepting it, creating a documented chain of custody from intake through return. Insurance coverage should also be confirmed upfront, since Article 9 recognizes that expenses related to preserving collateral, including insurance, may be incurred while it’s held.
What Happens If You Can’t Repay
Borrowers naturally want to understand the downside before pledging something valuable. Losing the asset isn’t the immediate consequence of a missed payment. Lenders typically follow procedures set out in the credit agreement and applicable state law, which generally require notifying the borrower of a default and offering a chance to resolve it, under the same Article 9 framework governing secured transactions in the U.S.
Contacting your lender early usually preserves the most options — repaying the balance, renewing the term, or making other arrangements before collateral is liquidated. If the debt truly can’t be resolved, the lender may sell the pledged asset, and Article 9 generally requires that sale to be commercially reasonable, with any surplus returned to the borrower after the debt and permitted expenses are covered.
Who Luxury Asset Lending Is Built For
This type of lending suits owners who have valuable assets, don’t want to sell them, and need liquidity without the delay of bank underwriting or the exposure of a credit check. It works particularly well for consolidating high-interest debt, funding a business opportunity, covering an emergency, or bridging a gap while a larger transaction closes.
It’s not the right fit if your qualifying asset is worth less than $10,000, since most products in this category require that minimum. It’s also not suited to anyone unwilling to have an item held as security for the term, since that pledge is exactly what enables the fast, no-credit-check terms in the first place.
Take the Next Step
If you own diamonds, gold, jewelry, or a luxury vehicle and want to know what kind of financing it could unlock, the fastest way to find out is a free valuation. Vasco Assets, a licensed and bonded investment firm based in Newport Beach, CA, offers both LuxLoc and collateral loan options so you can choose the structure that fits your situation.
There’s no cost to explore what your assets could unlock, and no obligation to move forward once you do. Reach out for a no-obligation valuation and see what’s possible.
Frequently Asked Questions
What is luxury asset lending?
It’s a form of financing where a valuable physical asset, like diamonds, gold, or a luxury vehicle, serves as collateral instead of your credit score or income.
How is luxury asset lending different from a bank loan?
A bank loan evaluates your credit history, income, and financial profile, as outlined by the CFPB. Luxury asset lending instead evaluates the pledged asset’s value, condition, and market demand.
What assets qualify for luxury asset lending?
Diamonds, jewelry, gold, precious metals, and select luxury vehicles like Ferrari, Rolls-Royce, Bentley, and McLaren qualify, provided they’re valued at $10,000 or more.
What’s the difference between a collateral loan and a line of credit?
A collateral loan disburses a lump sum immediately that you repay right away. A line of credit like LuxLoc lets you draw funds as needed, paying interest only once you actually use it.
How much can I borrow against my asset?
Generally up to 80% of the asset’s appraised value, though the exact amount depends on professional appraisal, condition, and current market demand.
Will this affect my credit score?
No. Luxury asset lending through Vasco Assets requires no credit reporting and no credit inquiry, so it never touches your credit bureau file.
What happens if I can’t repay my balance?
Lenders generally must notify you of a default and follow procedures set by the credit agreement and state law before selling pledged collateral, under Article 9 of the UCC. Contacting your lender early usually preserves the most options.