
Financing Your Real Estate Purchase: How LuxLoc Secured Line of Credit Can Act As A Bridge
You have found the right property at the right price, but the timing is wrong. Your cash may be tied up in a home that has not sold yet, your mortgage approval may still be weeks away, or the seller may want a fast, clean close. In real estate, many buyers lose out in the gap between an opportunity and available capital.
Vasco Assets designed LuxLoc to fill that gap. LuxLoc is a first-of-its-kind secured line of credit backed by diamonds, gold, fine jewelry, and luxury vehicles. It has no hard credit inquiries, no appraisal fee, and no origination fee. You don’t have to sell the assets you value. You put them to work as a bridge to your next property.
Why Timing Is the Hardest Part of Buying Real Estate
Most real estate deals fall apart because money is not in the right place at the right time, not because of price. Buyers who must sell before they buy, investors chasing fix-and-flip or off-market deals, and business owners with hard-to-document income all face the same problem. The purchase deadline arrives before the funding does.
Traditional lenders rarely move at the speed of a competitive market. Bank bridge loans and home equity lines often require full financial disclosure, income verification, appraisals, and credit checks that can take weeks. A ready source of capital lets you present a strong, non-contingent offer instead of hoping the timeline works out in your favor.
What Is LuxLoc and How Does It Work as a Bridge?
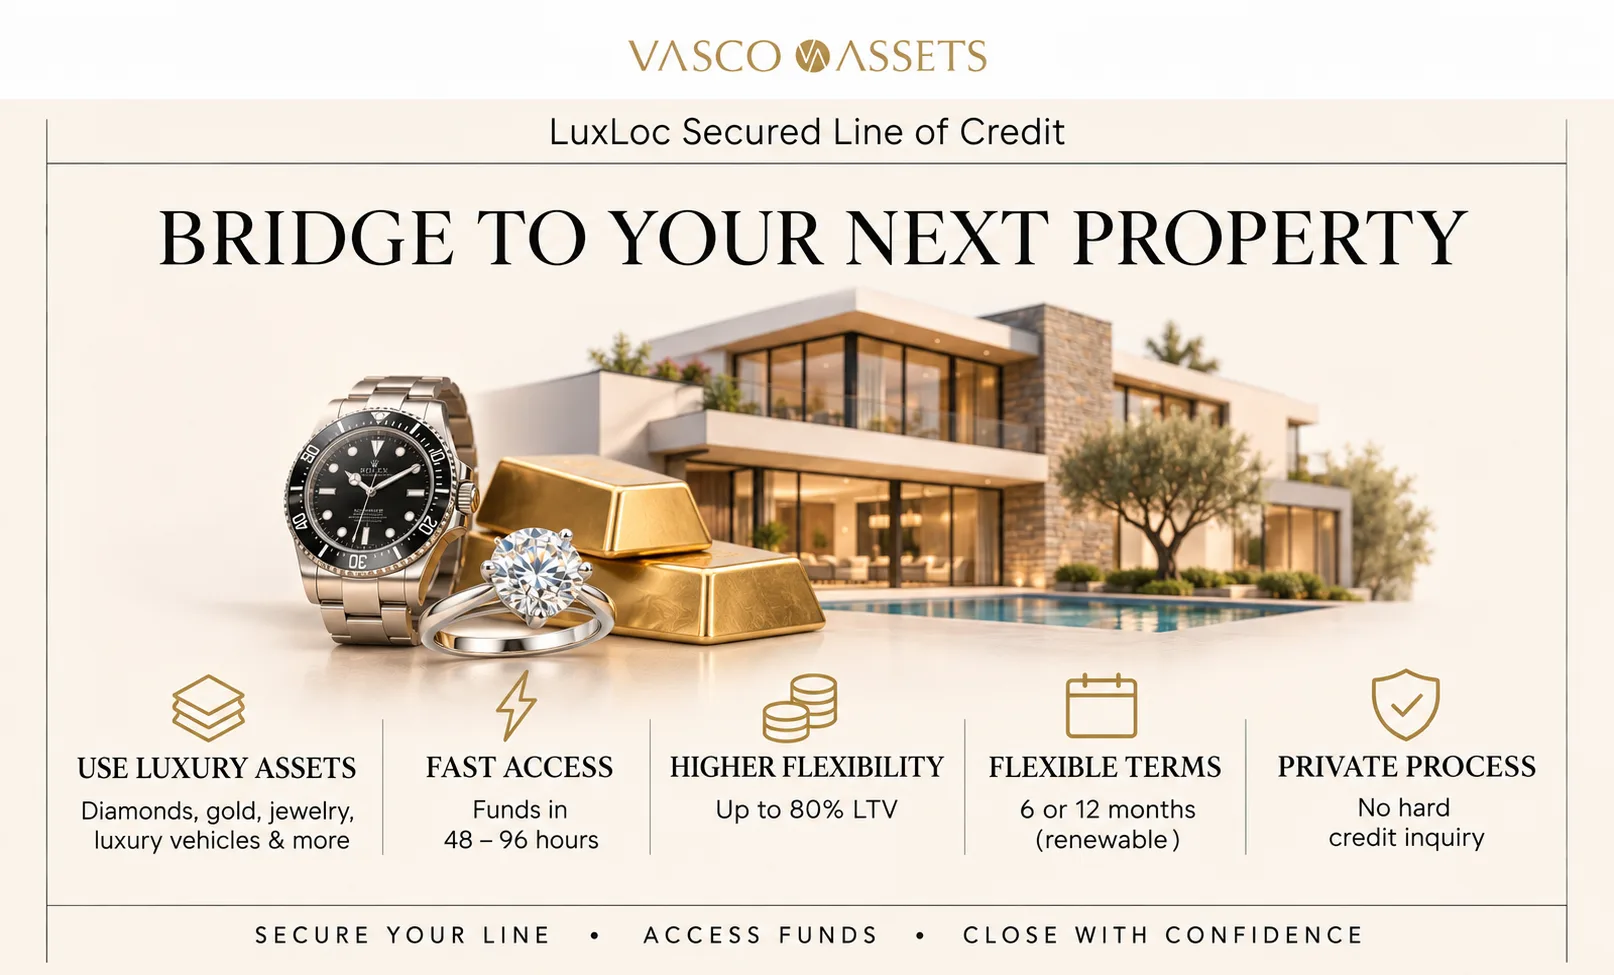
LuxLoc is a credit line secured by tangible luxury assets rather than by your credit score or tax returns. Eligible collateral includes diamonds, jewelry, gold, precious metals, and luxury vehicles valued at $10,000 or more. Vasco Assets offers loan-to-value ratios of up to 80%. Standard lines run from $20,000 to $99,999, with customized terms above $100,000.
LuxLoc separates securing credit from using it. You establish the line for roughly 0.5% of the amount you may want to borrow, and interest begins only when you draw funds. When a property becomes available, funds are allocated within 48 to 96 hours once documents are issued. After your previous home sells or your long-term financing closes, you repay the balance and reclaim your assets.
LuxLoc vs. Traditional Bridge Loans and HELOCs
A traditional bridge loan or HELOC uses your existing home as collateral, which ties your new purchase to the sale of your current property. If that sale stalls, the pressure builds quickly. These products also usually involve appraisals, origination fees, income documentation, and hard credit inquiries, all of which add cost and time to an already demanding process.
LuxLoc keeps your real estate out of the equation. Vasco Assets securely holds, insures, and stores your collateral, and your homes stay unencumbered. Terms run six or twelve months and can be renewed while you remain in good standing. Collateral is re-evaluated every six months, so if your assets appreciate, your available credit can increase.
Can You Use a Luxury Asset Line of Credit for a Mortgage Down Payment?
Yes. Funds borrowed through a luxury-asset-backed line of credit like LuxLoc may qualify for a mortgage down payment, depending on the loan program and lender requirements. However, borrowing against valuable assets does not automatically guarantee mortgage approval. Understanding how lenders view these funds before you make an offer helps you avoid surprises at the underwriting stage.
According to Fannie Mae’s Selling Guide B3-4.3-15, conventional mortgage borrowers can use loans secured by qualifying assets, including automobiles, artwork, and collectibles, for down payments, closing costs, and financial reserves. Fannie Mae treats these funds as a return of equity, because you are borrowing against something you already own.
How Does LuxLoc Affect Mortgage Qualification?
LuxLoc does not require a hard credit inquiry, but mortgage lenders must still evaluate your financial obligations. Under Fannie Mae’s debt-to-income guidelines, your qualifying monthly debt payments are compared against your gross monthly income to determine how much home you can afford.
For example, if a LuxLoc draw creates a $500 monthly repayment obligation, that amount may increase your debt-to-income ratio and reduce how much mortgage financing you qualify for. Even when a secured loan has no scheduled monthly payment, lenders must calculate an equivalent amount and count it as recurring debt. Ask how LuxLoc’s 30-day maintenance fee will be treated as well.
What Documentation Will Your Mortgage Lender Need?
Under Fannie Mae’s guidelines, your lender must document three things: the terms of the secured loan agreement, evidence that the collateral lender is not a party to the property sale, and proof that the borrowed funds were transferred to you. FHA and other mortgage programs have different eligibility requirements, so not every program accepts luxury-asset-backed proceeds.
Before using LuxLoc for a real estate purchase, consult your mortgage lender. Confirm that the funds qualify under your specific loan program and that the additional borrowing will not jeopardize your mortgage approval. Your LuxLoc agreement and funding records give your lender the paperwork it needs to complete that review.
Why Buyers Choose Vasco Assets for LuxLoc
Vasco Assets is a licensed and bonded private investment firm headquartered in Newport Beach, California. Its team brings more than 150 years of combined experience in luxury buying. Certified diamond buyers and asset specialists evaluate your items carefully, so your credit line reflects their true market value rather than a cautious, lowball estimate.
Clients praise the company’s transparency, competitive rates, and personal service, and it has more than 100 five-star reviews online. If a property purchase is on your horizon, secure your line before you need it. Apply for LuxLoc, call 949.674.3575, or request a free valuation to see how much buying power your assets can unlock.
Conclusion: Turn Your Luxury Assets Into Real Estate Opportunity
Real estate rewards buyers who can act quickly and confidently. LuxLoc bridges the property you want and the financing or sale proceeds you are waiting on. You avoid credit inquiries and appraisal fees, and you keep the assets you would rather not sell. Paired with early guidance from your mortgage lender, it can make your offer more competitive.
Your diamonds, gold, and luxury vehicles already hold significant value, and Vasco Assets can turn that value into the capital that closes your next deal. Email info@vascoassets.com or visit the office at 2024 Quail Street in Newport Beach to start your LuxLoc application today.
Frequently Asked Questions
Can I use LuxLoc for an investment property or fix-and-flip?
Yes. LuxLoc funds can be used for any purpose, including earnest money, renovations, auction purchases, and off-market deals where speed matters. Approval is based on your collateral rather than your financial statements, so it also suits self-employed buyers whose income is complex to document.
How quickly can I access funds for a real estate deal?
Once your line is established, funds are allocated within 48 to 96 hours of your call for funds and the issuance of documents. Because the collateral evaluation happens upfront, you can respond quickly when an offer is accepted or a deposit comes due.
Will applying for LuxLoc affect my credit score?
No. LuxLoc involves no hard credit inquiries and is not reported to the credit bureaus. If you are applying for a mortgage, you should still disclose the line, because your lender may count any repayment obligation toward your debt-to-income ratio.
What assets qualify for LuxLoc?
Eligible assets include diamonds, jewelry, gold, precious metals, and luxury vehicles such as Ferrari, Maserati, Rolls-Royce, Bentley, and McLaren. Collateral must be valued at $10,000 or more. Items below that threshold may qualify for a Vasco Assets collateral loan instead.
How much can I borrow through LuxLoc?
LuxLoc offers loan-to-value ratios of up to 80%, depending on the asset. Standard lines range from $20,000 to $99,999, with customized terms available above $100,000. Your exact limit is set after Vasco Assets evaluates your collateral, and there is no appraisal fee.
What fees are involved with LuxLoc?
There are no origination, appraisal, or hidden fees. Securing the line costs approximately 0.5% of the amount you may want to borrow, and interest applies only to funds you draw. A maintenance fee, due every 30 days, covers insurance, storage, and administration, and it applies whether or not you use the line.
What happens if I need more time before my home sells?
LuxLoc terms run six or twelve months, and clients in good standing can renew and extend. If a payment is missed, a 10-day grace period applies, during which a late fee accrues. Talk with the Vasco Assets team early so your term matches your real estate timeline.